Why I think Unilever could disappoint

Unilever is one of the most popular stocks among dividend-focused investors. As one of the world’s largest consumer goods companies its products include a huge range of well-known brands, from Dove soap to Magnum ice cream and Comfort fabric softener.
Over many decades the company has grown its dividend above the rate of inflation, which is precisely why it is so popular with investors.
But despite Unilever’s excellent track record, I think the odds are that its shares will not perform as well in the future as they have in the past.
Here's why.
Unilever has a great track record, of that there is little doubt
Any company that grows its dividend for decades on end is likely to have a very strong competitive position, and that is definitely the case with Unilever.
Many of its products have leading market positions and are well-regarded by customers, which enables the company to avoid competing on price alone.
In other words, Unilever can sell its Magnum ice cream at a higher price point than less well-known ice creams, even if its competitors are of equal quality.
Many shoppers will still choose Magnum, despite its higher price, simply because they have seen the glitzy adverts and perhaps even tasted the ice cream before, whereas they have probably never heard of or tasted the other brand.
This allows Unilever to generate higher profit margins than it would be able to otherwise, which in turn allows it to invest heavily into product development through R&D and brand development through advertising.
This virtuous circle has driven the company’s growth for decades and continues to drive it today:
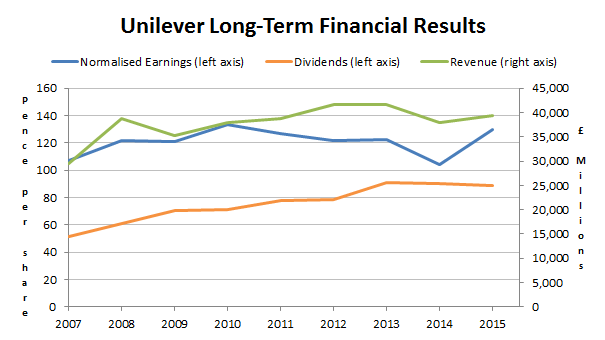
- 10-Year growth rate = 3% (FTSE 100 = 2%)
- 10-Year growth quality = 67% (FTSE 100 = 50%)
- 10-Year profitability = 15% (FTSE 100 = 10%)
Unilever manages to beat the FTSE 100 across each of the key financial metrics that I use, so its performance is clearly above average (assuming the FTSE 100 represents the average large-cap company).
Its growth does not require heavy investment in acquisitions or capital assets
As part of my value trap analysis I also look at a company’s capital expenses and acquisitions. My goal is to be especially careful around companies that have to or have chosen to invest heavily in either capital assets or other companies.
In terms of capital expenses, over the last ten years Unilever spent an average of 38% of its post-tax profits on capex. That figure of 38%, which I call the capex ratio, is relatively low.
My rule of thumb for capex is:
- Be wary of investing in companies where the capex ratio is above 100%
With a capex ratio of just 38%, Unilever’s capex requirements do not raise any alarm bells.
In terms of acquisitions, Unilever has also managed to avoid this sometimes dangerous path to growth.
Although it does consistently acquire other companies, none of its recent acquisitions have cost it more than a single year’s profit (my definition of a large acquisition), which means it passes another one of my rules of thumb:
- Be wary of companies that have made large acquisitions in the last ten years
As with capex, a high level of acquisitions doesn’t necessarily mean I won’t invest in a company, but it does mean I’ll have a good look at any large acquisitions to see how their integration is progressing.
Financial obligations also appear to be under control
There are two main balance sheet items which I pay close attention to: borrowings and pension liabilities.
I compare each to the company’s five year average normalised post-tax profits, the result of which I call (somewhat uninspiringly) the debt ratio and the pension ratio.
Unilever’s total borrowings are currently £10.6bn, its pension liabilities are £17.0bn and its average profits are £3.5bn.
As a result Unilever has the following financial obligation ratios:
- Debt ratio = 3.0
- Pension ratio = 4.8
The associated rules of thumb are:
- Only invest in a defensive sector company if its debt ratio is below 5
- Only invest in a company if its pension ratio is below 10
- Only invest in a company if the sum of its debt and pension ratio is below 10
Unilever passes all of these tests and so once again it ticks the box as a relatively safe company, at least in terms of its financial obligations.
By every measure then, Unilever is just the sort of company I like to invest in. It is growing steadily, with a reliable dividend, has good competitive advantages from strongly branded products and relatively conservative financial obligations.
So why am I not investing?
Quite simply, I don’t think the share price currently represents good value for money.
The price paid for a company is just as important as its quality
Unilever’s share price is currently 3,160p. At that price it has the following valuation ratios (compared to the FTSE 100 at 6,200):
- Dividend yield = 2.8% (FTSE 100 = 4.2%)
- PE ratio = 24.4 (FTSE 100 = 28.0)
- PE10 ratio (price to 10yr average earnings) = 26.1 (FTSE 100 = 14.3)
- PD10 ratio (price to 10yr average dividend) = 41.8 (FTSE 100 = 28.5)
The only measure where Unilever appears to be cheaper than the market average is the PE ratio, which is also my least favourite metric as it can be very unreliable.
Looking at the other ratios, Unilever currently trades at a fairly hefty premium to the market with higher valuation ratios and a lower yield.
However, that premium price could be justified if the growth, quality or profitability of the company made up for it. After all, a Rolls-Royce Phantom is more expensive than a Ford Mondeo for entirely justifiable reasons.
In this case, while Unilever’s track record may be good enough to justify its current share price, I don’t think it is good enough to make that share price look particularly attractive.
For example, if Unilever can continue to grow by 3% a year (as it has in the recent past) and if the dividend yield stays at 2.8%, then shareholders will receive a total return of 5.8% per year.
I don’t know about you, but an expected return of 5.8% per year does not exactly set my pulse racing.
Of course I could be wrong and the company could grow much faster than 3%. Or perhaps the share price will continue to go up faster than the dividend, withering away at the already thin yield. But I don’t think it’s obvious why either of those outcomes should occur.
What price would I pay for Unilever?
As a general rule I want my portfolio to be:
- High return: Beat the FTSE All-Share by at least 3% a year (or alternatively to get a return of at least 10% a year)
- High yield: Have a yield which is at least 110% of the All-Share’s yield
- Low risk: Be less volatile and less risky than the All-Share (which is why I’m interested in companies like Unilever)
Given Unilever’s mediocre rate of growth, I need a much higher dividend yield than 2.8% in order for my capital gains and dividend income targets to be met.
For me to even consider investing I would want Unilever’s share price to drop back down to 1,800p at the very least.At that price the the dividend yield would be 5% and the company would rank near the top 50 stocks on my watch list, which is where I like to go shopping for new investments.
Of course for the share price to fall that far the company would have to be facing some obvious problems, but that would not bother me, as long as those problems were fixable and unlikely to cause permanently damaged to the company’s long-term prospects.
At 1,800p, with a yield of 5% and an estimated dividend growth rate of 3%, the expected return would be 8% per year.
That’s still below my target rate of 10%, but with a bit of luck, and if the storm clouds cleared, the shares could be re-rated back upwards within a few years.
That would probably add at least another couple of percentage points to the rate of return. But currently there are no storm clouds, and until they appear Unilever will have to stay on my watch list as an attractive company with an unattractive share price.
(Just out of interest, when I reviewed Unilever a year ago my target price was also 1,800p. Despite Unilever’s growth since then, other stocks have become cheaper as the market has declined, which is why Unilever’s target price has not moved upwards)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
5 comments
Circa 6% less about 2% inflation gives about 4% equity premium, in line with historical numbers. If equity markets do (much) better than that, it will be an historical outlier.
Quality stocks are not particularly pricey if you look at relative prices. Investing is about choosing the best available instrument in the menu of currently available options -- you cannot trade at past (or future) prices unfortunately.
And yet the Share Centre rate it as a buy mainly because of it improving performance and reputation.
They could be right to say that; after all, the future is an uncertain place. But I just don't see an obvious reason why the shares would outperform over a five or ten year period.
According to your own valuation, the market just needs to do below 5.8% for Unilever to outperform the average, which doesn't seem too challenging. Such stocks tend to be perennially modestly undervalued, maybe because people too easily think they're fully priced and boring...
Hi cig
Good point, but beating a lame duck (the FTSE 100 if it returns less than 5.8% a year over say a decade) isn't much of an aspirational goal. I prefer to aim at an annualised return of more than 10% and not invest in anything where I can't come up with a reasonable explanation as to why it might be able to achieve that.
I can't see why Unilever is likely to generate a 10% annualised return going forwards, so I won't invest, even if it does beat a market that returns a measly 5.8% per year.
As for perennial undervaluation, I think that's probably right, although perhaps not recently as many of these defensive stocks have been bid up to very high levels by those who want a low risk yield.